You can value a token through three approaches, each tied to what the token does in its system: as a medium of exchange (via the equation of exchange, M × V = P × T), as an access coupon (via discounted par value), or as equity (via discounted cash flow). The right approach depends on the token's role in the economy, not on what's trendy, and the three often produce very different numbers for the same project.
Why this question gets asked
Every token has a price, and somewhere between the fundraise and the first unlock someone has to defend it. Whether that number came from a spreadsheet, a comparable, or someone's intuition at 3 AM, the underlying question is the same: what is this token actually worth? The framing has shifted since 2019. Fundraising no longer runs through ICOs and STOs, it runs through launchpads, direct listings, and structured airdrops to retroactive users. The valuation question has not shifted.
This article covers three valuation frames that each map to a different kind of token: medium of exchange, access coupon, and equity. They produce very different numbers for the same project because they measure different things. Which one applies depends on what the token actually does in the system, not on which one produces the friendliest number. If you are still pinning down the token's role, the companion piece on token value drivers is the prerequisite.
The NPV backbone
All three approaches lean on the same backbone: discounting future value to present value. Net present value takes a series of cash flows and reduces them by a rate that reflects how risky those cash flows are. The math is standard corporate finance, applied to tokens the same way it applies to any other asset.
Where CFt is the cash flow at period t, r is the discount rate, n is the number of periods, and TV is the terminal value. Terminal value captures everything after the forecast horizon, when the business has reached its steady-state growth rate. Without it, any finite-horizon DCF undervalues a going concern by silently assuming the business dies at year five.
Here g is the long-term growth rate of the company at maturity, not at inception. The math is the easy part. The real argument in any token valuation lives in the inputs.
The discount rate r is where most token valuations go wrong. The current 5-year US Treasury yield sits around 3.63%, which anchors the risk-free rate. If an investment carried the same risk profile as a government bond (which tokens never do), you could use a similar rate. For anything else, the rate has to reflect the additional risk. Discount rates of about 10% are pretty standard, going up to 15% for riskier projects. I have seen token valuations in the crypto space run as high as 40%. I disagree with such high numbers. If your project needs a 40% discount rate, restructure your project first to reduce the risk.
The worked example: BreadCoin
Let's use a fictional platform to keep the scenarios concrete. BreadCoin is the native token of an online platform that connects local bakeries with customers. The platform does not sell bread itself, it facilitates transactions. Each bakery pays a $100 annual listing fee, and the platform takes 5% of each transaction.
In year one, 1 million loaves are sold across 1,000 bakeries at an average price of $2 per loaf. Annual operating expenses run $100K. During the initial token sale, the team raised $100K by offering 500,000 BreadCoins at $0.20 each. Sales grow 20% year over year, expenses grow 10%, and taxes are flat at 20%. That produces the five-year projections below, which all three valuation approaches will build on.
| Year 1 | Year 2 | Year 3 | Year 4 | Year 5 | |
|---|---|---|---|---|---|
| Platform turnover | $2,200,000 | $2,640,000 | $3,168,000 | $3,801,600 | $4,561,920 |
| Revenue | $200,000 | $240,000 | $288,000 | $345,600 | $414,720 |
| Free cash flow | $80,000 | $88,000 | $96,800 | $106,480 | $117,128 |
Approach 1: Token as currency
This is the model most token launches have used since 2017, often without realizing it. The logic traces back to the quantity theory of money and the economist's favorite identity, the equation of exchange. It is the cleanest valuation approach on paper, and the hardest to pin down in practice.
Where M is the money supply in circulation, V is velocity (how often money changes hands per year), P is the price per transaction, and T is the number of transactions. P × T is the total economic output of the system, which for BreadCoin is platform turnover. Chris Burniske formalized the crypto application of this equation.
The sharpest critique came from Vitalik Buterin, who pointed out that most projects using this model are effectively selling someone else's product. For BreadCoin: give us money to build a bread platform, and in exchange you can buy bread with our token; the bread itself is provided by someone else, not by the platform team. The critique is not fatal, but it is a warning. The model only works when the token's demand is actually load-bearing for the platform.
Solving for the token price is not as clean as the equation suggests. The left side is denominated in BreadCoin, the right side in dollars, so we need to expand it to reconcile the units. That requires introducing an explicit token-to-fiat exchange rate.
Where ET/F is the token/fiat exchange rate, MT is the supply denominated in tokens, and PF × T is platform turnover denominated in fiat. Rearranging for the token price gives the fair-value expression most practitioners actually use. It is the same equation, just reshaped so token price sits on the left.
Velocity is where this model falls apart. Bitcoin's on-chain velocity, Ethereum's, and the M1/M2 USD velocities all sit in different ranges, and the same asset shows wide variance across periods. Speculators holding tokens, locked staking, burn addresses, and rewards all change it. Accounting for those sinks, the expanded form looks like this:
Running the simplified equation with V=30 on BreadCoin's turnover puts the token price in the teens of cents for year one. Adding sink adjustments (tokens held by speculators, locked in staking, or sent to burn addresses) drops the effective M meaningfully. The chart below shows the trajectory under the fuller model, not the simplified version.
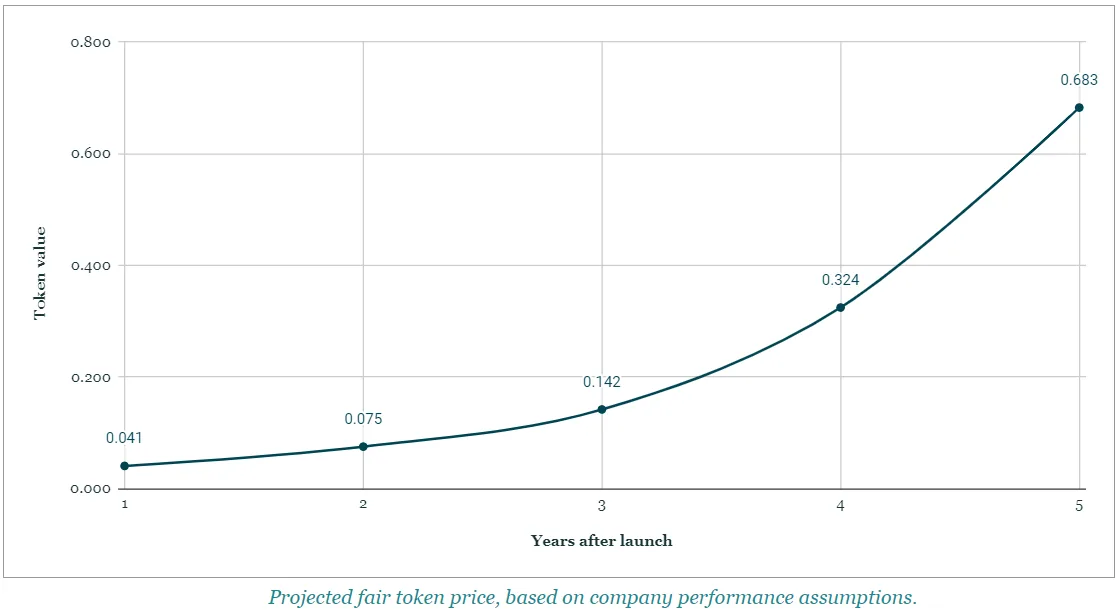
The number is real, but the exercise is full of holes. If any of the token sale participants are investors rather than platform users, the effective circulating supply is smaller than the total supply. If the token is speculatively held, V drops and price rises, but that is not a stable source of value. Use this approach when the token genuinely has to change hands to make the platform work. Pinning down the number then requires modeling velocity, sink terms, and burn dynamics under uncertainty, which is what a tokenomics simulation engagement actually produces.
Approach 2: Token as access coupon
This is the approach Vitalik actually endorsed as economically stable, and it is rare in the wild. In this model, only the platform's own fees are payable in BreadCoin, everything else settles in another currency. The token is a prepaid coupon for a known unit of service.
The mechanic: set a par value the token redeems for. If BreadCoin sold at $0.20 during the initial sale, one BreadCoin should redeem for more than $0.20 once the platform is live, or the buyer has no reason to participate. Say par value is $0.50 in year one, $0.70 in year two, and so on, rising each year to give holders a reason not to dump the whole stack in week one. A rising par schedule also gives new buyers a reason to participate in secondary sales after the initial offering.
Vitalik's argument, in his 2017 essay on medium-of-exchange token valuations, is that if the developers themselves are selling access to their own service, the arrangement is essentially a Kickstarter and economically stable. The token is backed by something the developer actually delivers, so buyer and seller expectations line up. The critique of this approach is simple: the math only works if the project can afford to subsidize the gap between sale price and par value out of its own pocket.
Selling 500K BreadCoins at par value $0.50 commits the platform to $250K of fees that will not be collected in cash. With $200K of projected year-1 revenue, the team is effectively giving away year one to make the coupon work. Most teams cannot afford that. A secondary friction: return on investment for this token is not really meaningful because it can only be used on the platform, and secondary markets can only trade below par value, which bounds the upside. That is also why access tokens often do better unlisted.
Approach 3: Token as equity
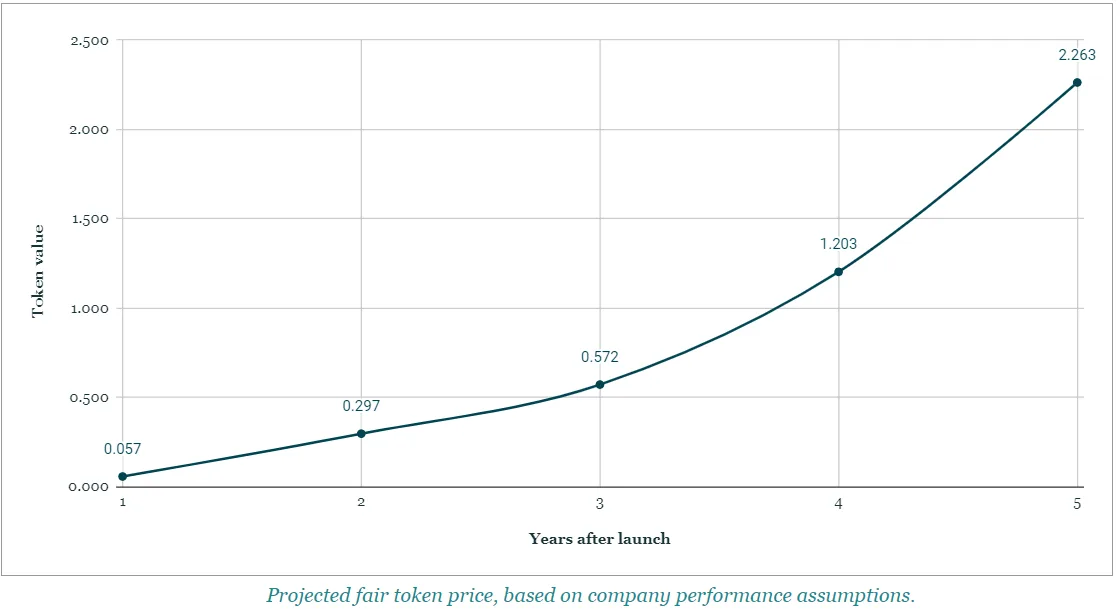
If the token represents a claim on the company's cash flows, valuation collapses into a standard DCF. The formula is the one from earlier, applied to projected free cash flow over the forecast horizon plus a terminal value for what comes after. For BreadCoin, with year-5 cash flow of $117K, a long-term growth rate of 8%, a discount rate of 15%, and 500K tokens fully equity-backed, the DCF gives a fair token value of around $2.26 per token. That is over 10x the initial sale price, which is the number every token team wants.
A few things the math glosses over. The $2.26 figure assumes 100% of company equity is tokenized, which is rare in practice. If only 10% of equity goes to tokens (closer to a normal structure), the fair value collapses to roughly $0.23 per token, barely above the ICO price. The chart below shows the fair token price year by year under the full 100%-equity model.
The equity model is the easiest to justify on paper and the hardest to actually deliver. Tokenizing 100% of a company is a tax, regulatory, and governance mess. Tokenizing 10% produces numbers that look disappointing next to the equation-of-exchange fantasy. Both are honest. The equation-of-exchange number usually is not.
Which approach to use
Here is the practitioner read, with 300+ projects behind it. Pick the approach that matches what the token actually does, not the approach that produces the friendliest number.
- If the token is required to make the platform function (gas, settlement, native medium of exchange), the equation-of-exchange model applies, but only if you model velocity and sinks seriously.
- If the token is a prepaid service coupon with bounded upside, the access model applies, and the project should think twice before listing on secondary exchanges because artificial scarcity makes it worse.
- If the token is a claim on cash flows, it is a security in every jurisdiction that matters, and the DCF applies along with the securities law that applies with it.
The failure mode I see most often is teams choosing the approach that gives the biggest number and reverse-engineering the token mechanic to justify it. That works in a bull market and blows up in the first bear. The better sequence is the other direction: decide what the token does for the economy, then pick the valuation frame that fits, then live with the number that comes out. For more on how that mechanic choice gets made upstream, the tokenomics design 101 piece walks through the decision tree.
Frequently Asked Questions
01Why do utility tokens often trade well below fair value from a DCF model?
+
02Is token velocity still a useful concept for modern DeFi protocols?
+
03How do vesting schedules and cliffs affect token valuation?
+
04When should a project skip token valuation entirely?
+
05Can you combine DCF and the equation of exchange in one model?
+